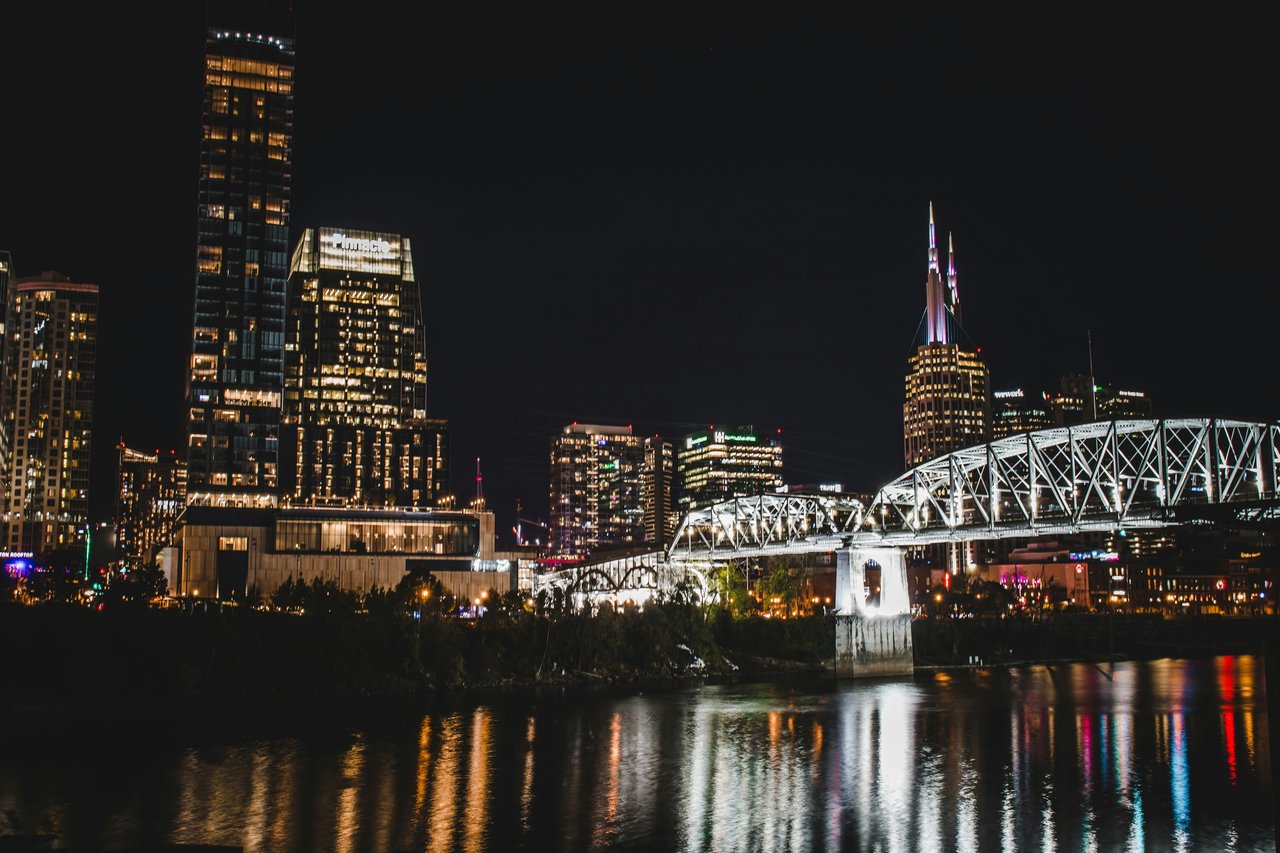
Nashville STR Cash on Cash Return: The Year-by-Year Compression
Occupancy rates in Nashville's short-term rental market peaked near 67% in 2021. By mid-2026, AirDNA is tracking the market at 54% occupancy across 13,898 active listings — with average revenue per listing now sitting at $40,900 annually, down 6.1% from June 2025 to June 2026. That compression did not happen overnight, and it did not happen for one reason. It happened in layers, one year at a time, and understanding the sequence is the only way to accurately underwrite a Nashville STR purchase today.
2021: The Anomaly That Set the Expectations
The 2021 Nashville STR market was, by every measure, abnormal. The outsized returns many owners experienced in 2021 and 2022 were driven by extraordinary conditions, not a permanent baseline. Pandemic-era revenge travel flooded the city. Supply was thin. Operators who had survived 2020 entered 2021 with deeply discounted debt service on pre-rate-hike mortgages. The result was a window where almost any asset in a good Davidson County zip code printed cash.
Nashville was the poster child of the STR investment boom. Every podcast, every guru, every "passive income" course pointed investors toward Nashville. A three-bedroom house with a generic listing and stock photos was enough to fill a calendar in 2021. Cash-on-cash returns in the 12% to 18% range were genuinely achievable on well-located properties with owner-occupied permits or grandfathered commercial-zone access. That range became the benchmark new buyers carried into underwriting for years after the conditions that produced it had vanished.
2022: The Permit Freeze and the Rate Shock Hit Simultaneously
Two things happened in 2022 that permanently altered the Nashville STR return equation, and most investors focused on only one of them.
The regulatory side: Metro Nashville effectively stopped issuing new non-owner-occupied STR permits in residential zones, a policy that had been taking shape since 2021. Non-owner-occupied STRs in residential zones were effectively banned for new permits starting in late 2021-2022. The city stopped issuing new non-owner-occupied STR permits in single-family residential areas. Owner-occupied permits still exist but require the owner to live on the property and have a cap of 3 rooms. That constraint did not suppress supply as much as it was supposed to. Commercial and mixed-use zones — Germantown commercial, SoBro, the Gulch, and Music Row-adjacent commercial corridors — remained more permissible for investor STRs. Builders and developers continued stacking inventory in those corridors through 2022 and into 2023.
The financing side: Rapid interest rate hikes between 2022 and 2023 raised mortgage costs significantly. The average 30-year mortgage rate jumped from around 4.2% to 6.5%, making new STR acquisitions and refinancing more expensive. That mattered enormously for the cash-on-cash math. A property acquired at $550,000 with a 4% rate carried roughly $2,100 per month in debt service on a standard 20% down conventional loan. At 6.75%, the same purchase structure pushed debt service above $2,850 per month — an additional $9,000 per year in fixed costs, before a single booking.
Occupancy held in this period. Occupancy improved from 50% in 2022 to approximately 53% by 2023. Revenue held. The return compression was mostly invisible in the top-line numbers. It was buried in the debt service column, and new buyers were still projecting 2021-style revenue onto 2022-style acquisition costs.
2023: Supply Caught Up to Demand
Investor activity slowed, with new STR listings growth decreasing from 22% in 2022 to about 7% in 2024. But the inventory that had been added during the 2021-2022 rush was now fully operational and competing. Investors had followed suit, snatching up units in STR-permitted zones like The Nations, East Nashville, and downtown's Gulch district. Today, the city is flooded with thousands of short-term rental options, many offering similar layouts, amenities, and aesthetics. With such an oversupply, it became harder than ever to stand out — and even harder to keep rates high.
Average daily rates reached record highs in 2023, rising from $340 in 2022 to $350, pushing RevPAR to about $186 — up 6% year-over-year. That headline looked healthy. But RevPAR gains were concentrated in the top-performing listings. The median operator was not seeing $350 per night. They were competing with 50 similar properties on the same block.
This is where the Nashville STR cash on cash return started to split by tier. Operators who invested in amenities, photography, and dynamic pricing held their returns. Operators who treated their unit like a vending machine — the ones who captured the easiest cash in 2021 — began underperforming. That divergence accelerated through 2024.
For a deeper look at how we underwrite Nashville STR properties before any offer is made, the Costigan Group STR advisory page covers the full process, including the Nashville STR Underwriting Calculator we built for exactly this market environment.
2024: The Softening Became Undeniable
By late 2024, Nashville had approximately 13,450 active STR listings, reflecting an 8% year-over-year increase. Demand had not grown at the same rate. The result was what the STR data industry calls ADR compression — fewer premium nights to go around means each listing extracts less revenue per available night even when it stays technically "occupied."
Nashville's occupancy fell from approximately 66.7% to 54.3% — an 18.6% year-over-year drop by early 2025, according to StaySTRA data. That is not a rounding error. An 18.6-point occupancy decline on a property generating $60,000 in revenue at 67% occupancy means the same property is now generating closer to $48,000 — a $12,000 revenue drop. Run that against 2024 mortgage rates above 7% and property taxes that were quietly climbing before the formal reappraisal, and the cash-on-cash math for recent buyers got painful fast.
With 6.8% mortgage rates, most STR markets ran thin on cash-on-cash return at standard 20%-down financing — a reality that applied directly to Nashville buyers in this period. Investors who achieved 8% to 15% CoC returns typically combined one or more of the following: buying 10% to 20% below median, putting 30% or more down to reduce debt service, or selecting properties with revenue well above market median. Straightforward deals bought at full ask with conventional financing in 2023-2024 frequently penciled at 2% to 4% cash-on-cash — or negative, depending on operating cost assumptions.
2025: The Reappraisal Added a New Cost Layer
Just as investors were absorbing the revenue softness, Davidson County's 2025 quadrennial reappraisal landed. For the 2025 revenue-neutral reappraisal, property values were based on 2024 market data. The reappraisal showed a 45% median increase countywide. That number was not theoretical — the total property value in Davidson County soared to more than $220 billion, up 72% since 2020, according to the Tennessee Comptroller's Office, as reported by the Nashville Business Journal.
The reappraisal was revenue-neutral by state law, meaning the certified tax rate was required to fall proportionally. But Metro Council moved the rate above revenue-neutral. Davidson County property values had a 45% median increase countywide, and the mayor and metro council substantially increased the revenue-neutral tax rates to revenue-producing tax rates. For many STR owners, annual property tax bills jumped several hundred to nearly a thousand dollars over the prior year on the same asset — a cost increase that does not show up in any revenue projection tool and that cannot be offset by better photography or dynamic pricing.
Due to increased weather volatility — specifically severe storms and tornado risks — insurance premiums are also rising. Nashville averages are now higher than the national median. A typical policy for a median-priced home generally runs between $2,600 and $3,000 per year. For an STR owner, that premium is a direct cash-on-cash drag, and it has grown materially since 2021.
Where Nashville STR Cash on Cash Return Lands in Mid-2026
Here is the actual arithmetic at today's market conditions. Nashville's short-term rental market has 13,898 active listings as of June 2026. The average active listing earned $40,900 in revenue over the trailing twelve months. Listings were booked 54% of nights available at an average daily rate of $349. Gross revenue of $40,900 minus a standard 20-25% management and platform fee structure leaves roughly $30,700 to $32,700 in net revenue before debt service, property tax, insurance, and maintenance.
Take a mid-market STR purchase in Germantown or East Nashville at today's pricing — Davidson County's median sale price came in at $470,000 as of March 2026, per Redfin. At 20% down on a $470,000 purchase with a 6.75% rate, monthly debt service runs approximately $2,450, or $29,400 per year. After taxes (call it $7,000 annually post-reappraisal), insurance ($2,800), and reasonable maintenance ($3,500), you're looking at total operating costs plus debt service in the range of $42,700 per year.
Against $31,500 in net revenue, that is a negative cash position at the market average. Nashville's ROI Score of 59 out of 100 on Rabbu's proprietary scale places it in the "Attractive Opportunity" band, but above-average occupancy stability is the standout factor, while revenue-to-price ratio, market growth, and supply/demand balance all rate as average — meaning returns depend heavily on choosing the right property size and location.
That is not a reason to avoid Nashville STR investing entirely. It is a reason to stop buying at the median and expecting 2021 results. Top-10% performers in the Nashville market achieve $9,093 or more monthly. Strong-performing top-25% properties earn $5,900 or more, indicating effective management and desirable locations and amenities. The spread between median and top-quartile performance is wide enough that a well-selected, well-operated property can still produce a 6% to 10% Nashville STR cash on cash return. The market has not broken — it has bifurcated.
Nashville-Davidson's 5,790 active listings show active supply contracted 15% year over year, yet revenue and nightly rates both rose — fewer listings are capturing more of the market. Remaining and incoming hosts benefit from reduced competition and stronger pricing. That contraction is a meaningful signal: the weakest operators are exiting, and the performers who remain are absorbing a larger share of available bookings.
If you are evaluating a specific Nashville STR acquisition today, our team runs underwriting before the offer — not after. The Nashville STR Playbook and Underwriting Calculator we use are built for this exact environment, not the 2021 version of it. We have also been featured covering this market in depth — you can read the full USA Today feature on Nashville STR advisory for more on how we approach it.
The neighborhoods that still make sense — Germantown's commercial-zone pockets, SoBro, certain East Nashville corridors with high demand density — are documented in detail on our Nashville neighborhood guide. Location is doing more work now than at any point since 2019.
What Comes Next
RevPAR in Nashville was $181 as of mid-2026 — and from June 2025 to June 2026, RevPAR is down 9.8%, ADR is down 6.0%, and active listings are down 1.9%. The supply contraction is real but modest. The revenue softness is also real. The market is not in freefall — Nashville scores 83 out of 100 on AirDNA's Market Score, benchmarked against short-term rental markets nationally. That is a fundamentally sound market with a supply-demand imbalance that the regulatory freeze on new residential permits is slowly correcting.
The variable most investors are not watching closely enough is the insurance and tax cost trajectory. Both climbed materially from 2022 to 2026. Both are likely to continue climbing. Any pro forma that uses 2021 or 2022 expense assumptions against current revenue is producing a number that will not survive contact with reality. This is not an opinion — it is what the year-by-year data shows.
The current market is more selective. It rewards disciplined operators, thoughtful pricing strategies, and investors who understand when to refine operations and when to redeploy capital. If you are buying in 2026, your underwriting has to reflect 2026 — not the golden era that produced the returns you read about in 2021. The investors who understand that distinction are the ones actually making money in this market right now.
If you are trying to determine whether a specific Nashville property still pencils at current conditions, reach out directly. We will run the actual numbers — not the optimistic version — before you put anything under contract. That is what we do for every client who comes to us through our relocation and investment advisory work, and it is what separates a good purchase from a very expensive lesson.
Frequently Asked Questions
What was the average Nashville STR cash on cash return in 2021?
Precise market-wide averages from 2021 are not uniformly published, but well-located Nashville STRs with owner-occupied or grandfathered non-owner permits were widely producing cash-on-cash returns in the 12% to 18% range under 2021 conditions — thin supply, high post-pandemic demand, and mortgage rates still around 3% to 4%. Those conditions no longer exist, and projecting 2021 return benchmarks onto 2026 acquisitions is the single most common underwriting error we see.
Why did Nashville STR occupancy fall so sharply after 2021?
Nashville appeared in every "best STR markets" list precisely because it was performing well in 2021. But what made it attractive to investors also made it a target for every other investor reading the same lists. Supply data from 2022 and 2023 already showed Nashville was adding listings at rates that would inevitably suppress occupancy. More supply chasing the same travel demand means fewer nights per listing, which compresses both occupancy and operator revenue.
Can you still make money on a Nashville Airbnb in 2026?
Yes, but not at the median price point with conventional financing at today's rates. Top-performing Nashville STR listings — the top 10% — are achieving $9,093 or more per month. The path to positive cash-on-cash in 2026 requires buying below median, operating above median, or both. Markets like Germantown's commercial zone, SoBro, and select East Nashville pockets are still producing viable returns for disciplined operators with the right permit structure.
How did the 2025 Davidson County property reappraisal affect STR investors?
Davidson County's 2025 reappraisal was based on 2024 market data and showed a 45% median value increase countywide. Because Metro Council adopted rates above the revenue-neutral certified rate, many property owners saw tax bills increase by several hundred to nearly one thousand dollars annually on the same property. For STR investors, that is a direct reduction in cash-on-cash return that most 2022-era pro formas did not anticipate. It must be modeled explicitly in any current underwriting.
What is a realistic Nashville STR cash on cash return target for a 2026 acquisition?
At current acquisition prices ($450,000 to $550,000 in Davidson County), 6.5% to 7.5% mortgage rates, and average market revenue of $40,900 per year, most straightforward acquisitions will produce 0% to 4% cash-on-cash at median occupancy. Reaching 6% to 9% requires revenue above the market median — typically a two- or three-bedroom property in a high-demand zone with strong amenities, professional photography, and dynamic pricing. Properties bought 10% to 15% below median with larger down payments can also reach that range. Do not underwrite to the 12%+ returns from 2021.
Are there Nashville zip codes where STR returns still outperform?
Yes. Commercial-zone pockets in Germantown (37208), parts of SoBro and downtown-adjacent areas (37203), and select East Nashville corridors continue to generate above-average revenue density relative to purchase price. Active supply in Nashville-Davidson contracted 15% year over year through mid-2026, with revenue and nightly rates rising for those who remained — meaning the exits are freeing up bookings for the better-positioned properties. Permit status and zoning must be verified property-by-property before any offer.
Does Nashville's tourism demand still support STR investment?
Nashville's underlying demand engine remains intact. Nashville International Airport saw a record-breaking 22.9 million total passengers in 2023, a 14.8% increase from the prior year. Event-driven demand from CMA Fest, sports, and bachelor and bachelorette travel did not disappear — supply simply grew faster than demand over the 2021-2024 window. Markets still winning share in STR performance tend to have supply constraints, strong event calendars, and operators who invest in amenity differentiation — three factors Nashville can still deliver on the right asset.
Jack Costigan is the founder of The Costigan Group at Compass in Nashville, where his team has closed more than $100 million in real estate across Greater Nashville and Middle Tennessee. Specializing in luxury advisory, investment, and short-term rental real estate, Jack is known for a data-driven approach that helps buyers, sellers, and investors understand the numbers, the neighborhood, and the long-term value before making a decision. Featured in Apple News as one of Nashville's most sought-after short-term rental advisors, Jack pairs deep local expertise with modern marketing and a strategy-first approach to real estate. Learn more at thecostigangroup.com.