30 percentage points. That is the spread between the best and worst-performing Nashville STR submarkets, and the market-wide average tells you almost nothing about either end. Nashville's 13,898 active listings run 54% annual occupancy at an average daily rate of $349, according to AirDNA's June 2026 market report. But that number is an average dragged down by listings that are mislocated, underdifferentiated, and sitting outside the permit-eligible zones where real demand concentrates. If you are using 54% to underwrite a deal, you are likely either too optimistic or too conservative depending entirely on where the property sits.
This post is about the spread. Where it opens up, what drives it, and what the gap means for the buy decision.
The Nashville Airbnb Occupancy Rate in Context
From June 2025 to June 2026, Nashville's market-wide occupancy ticked up 1.7% year-over-year, even as average daily rate fell 6.0% and total revenue per listing dropped 6.1%. That combination — more nights booked, less money earned — is a compression signal. It means operators are discounting to fill calendars. The listings doing that discounting are almost uniformly the ones with the least locational leverage.
Nashville's RevPAR — the daily rate weighted by occupancy — sits at $181. That is the number that matters more than raw occupancy, and it collapses dramatically once you leave the core submarket cluster. A listing running 72% occupancy at $175 ADR produces nearly identical RevPAR to one running 54% at $230. The difference is the investor who bought the second property paid less for the asset and carries less risk when occupancy dips. Location is the lever.
Nashville scores 83 out of 100 on AirDNA's Market Score, which weighs rental demand, revenue growth, seasonality, regulation, and investability across more than 120,000 tracked markets globally. That score is real and it matters for market selection. But it does not protect a mislocated property inside Nashville from underperforming by 20 to 30 points on occupancy relative to its neighbors.
Downtown and SoBro: 75–85% and the Reasons Behind It
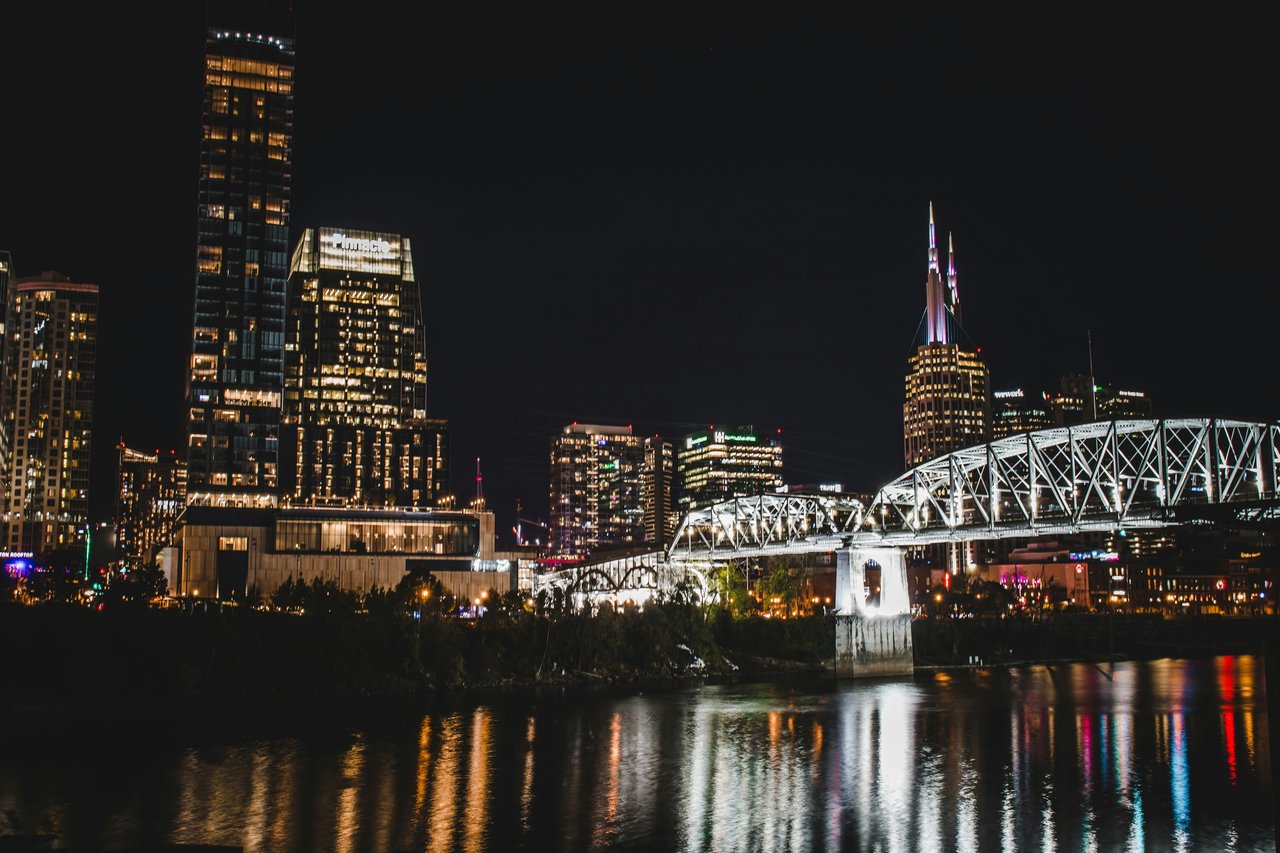
Downtown and SoBro capture group-booking demand like no other Nashville submarket. Bachelorette and birthday groups of four to eight people book two-to-four-night stays at $300 to $450-plus per night. That is not the only demand driver here — it is just the most visible one. CMA Fest in June, country music tourism every weekend, the Nashville Convention Center, two major healthcare conferences annually, the Predators NHL season October through April, the Titans NFL season, and bachelorette and wedding tourism every weekend April through November all layer into the same geography.
Published submarket data from BNBCalc documents Downtown Nashville occupancy running 75 to 85%, with ADR ranging from $289 to $450. Those are not optimistic projections — they are reported performance figures from a submarket with genuine structural advantages: walkability to Broadway, proximity to Bridgestone Arena, and the highest concentration of STR-legal zoning in Davidson County. Walkability to Broadway is the single strongest driver of nightly rate in the Nashville market, and it also drives occupancy because the demand pool of guests who want that experience is both large and specific enough that competition inside the submarket stays manageable.
The SoBro data is consistent with this. SoBro shows a reported occupancy rate of 79% with an average stay of 3.47 days and ADR of $346. The slightly shorter average stay compared to residential submarkets is not a weakness — it is evidence of the transactional bachelorette-and-event-weekend booking pattern that keeps the calendar full across more weeks per year.
In June 2026, CMA Fest generated a record $93 million in estimated visitor spending, with a record 100,000 fans in Downtown Nashville each day across the four-day festival, and downtown hotel occupancy hitting 89.4% during the event. What the hotel occupancy data confirms is that STR demand spikes equally hard in these windows — and the STR operator who sits two blocks from Broadway captures a meaningfully larger share of that overflow than one sitting in a residential neighborhood four miles away.
The Gulch: 80% Occupancy and the Corporate Demand You Are Not Pricing
The Gulch runs approximately 80% occupancy with an ADR near $350 and estimated annual revenue around $102,000 per well-positioned unit, according to BNBCalc submarket data. That performance is meaningfully above the city average, and the reason is a demand mix that most investors underestimate: corporate travel.
The Gulch is Nashville's most walkable luxury urban neighborhood, with direct access to Broadway and a strong year-round corporate traveler base — Amazon, Oracle, and AllianceBernstein are all headquartered nearby. Corporate travelers book longer, complain less, leave better reviews, and cancel less often than bachelorette groups. The Gulch runs both cohorts simultaneously: the event-weekend group booker and the midweek corporate guest. That double-demand structure is why the calendar stays full on Tuesday nights when downtown properties are softer.
A Ritz-Carlton hotel and residential building is planned for The Gulch near Kayne Prime , which signals institutional confidence in the submarket's long-term trajectory. For STR investors, that kind of luxury hospitality investment in the same neighborhood validates ADR at the top of the range and tends to pull up comps for the whole submarket.
Germantown and East Nashville: Consistent Demand, Different Logic
Germantown runs approximately 75% occupancy with an ADR near $220 and estimated annual revenue of $60,500. The lower ADR relative to Downtown is not a failure of the submarket — it reflects a different guest profile. Germantown guests book by name. They want the Victorian architecture, the dinner at Rolf and Daughters, the walk through the Saturday Farmer's Market at Bicentennial Mall. That is a repeat-booking, higher-review-average guest cohort, and it keeps the calendar full year-round rather than just on event weekends.
East Nashville demonstrates consistent year-round demand at depth, with roughly 2,019 active listings in the submarket. East Nashville STR operators report ADR near $175 and occupancy around 72%. That occupancy number deserves respect. 72% in a submarket with nearly 2,000 competing listings means the demand pool is genuinely large. East Nashville's guests are buying a feeling — the Five Points walkability, the Lockeland Springs residential character, proximity to Shelby Park. That is not the same guest as Broadway, but it is a durable one.
The caution in East Nashville is zoning. New non-owner-occupied STR permits are only issued in commercial, mixed-use, office, and downtown zoning districts, and those zones cluster within roughly three miles of Broadway across downtown, SoBro, the Gulch, Midtown, Music Row, Germantown, East Bank corridors, and slices of East Nashville and Wedgewood-Houston. Much of East Nashville's residential fabric sits outside those eligible zones. Buying a property there without permit verification first is an underwriting mistake that can kill the investment entirely. We walk through this in detail on the Costigan Group STR page.
Wedgewood-Houston: The Emerging Submarket That Is Earning Its Occupancy
WeHo is still working toward the occupancy levels of its neighbors, and that is precisely why some investors are paying attention to it now rather than later. AJ Capital Partners' 18-acre Wedgewood Village mixed-use development broke ground across all components in 2025, with Soho House and Hermès already open and confirmed 2026 arrivals including Momotaro, Pastis, and Live Nation's The Truth venue with 4,400 capacity. That is not a speculative future. It is permitted, funded, and under construction.
In November 2025, Bastion became one of Nashville's first Michelin-starred restaurants in WeHo. Fine dining at this level typically signals a neighborhood that has arrived — and that the buyer demographic is shifting upward. From an STR standpoint, Michelin-starred restaurants two blocks away are an amenity that guests mention in reviews and use when booking. It lifts perceived value and, over time, ADR.
Parts of WeHo carry a federal Opportunity Zone designation, providing significant capital gains tax advantages for qualifying investors. For STR investors who are weighing entry price against expected occupancy trajectory, the combination of below-Downtown pricing and genuine neighborhood velocity is a calculation worth running. The occupancy isn't Downtown today. In two years, the gap may be narrower than anyone expects. For more context on how Nashville's neighborhoods stack against each other for buyers and investors, see our Nashville neighborhoods guide.
The 27% Gap That Tells the Real Story
The most important occupancy data in Nashville is not the 54% market average. The median Nashville STR runs approximately 45% occupancy, and the bottom quartile of listings averages just 27%. That 27% figure is real and it represents a significant portion of the active permit holders in Davidson County. Those are not bad operators necessarily. They are largely good operators in the wrong locations.
The market averages $349 per night and 54% occupancy, but performance is product-driven: strong four-bedroom homes near downtown gross $80,000 to $160,000-plus per year, while average listings earn near $40,000. That four-to-one revenue ratio between the top performers and the average exists inside the same permit-legal zones. The variable is the product: bedroom count, amenities, rooftop deck, proximity to demand. The listing at $40,000 annual revenue is often one street or one building away from a listing at $120,000. The gap is not noise. It is the difference between a deal that pencils and one that does not.
Generally, 55% or higher occupancy is considered healthy, 65% or higher is strong, and 75% or higher indicates a high-demand market — but occupancy alone does not determine profitability. A listing with 50% occupancy at $400 per night earns more than one with 80% occupancy at $150 per night. This is the point most investors get backwards. They chase the highest published occupancy figure without running the RevPAR math. The Gulch running 80% at $350 ADR produces $280 RevPAR. East Nashville running 72% at $175 ADR produces $126 RevPAR. Both are performing well. The East Nashville investment makes sense only if the entry price reflects the RevPAR differential.
The One Rule That Governs All of This
Occupancy is a function of location, zoning, product, and operations — in that order. You can optimize product and operations. You cannot retrofit location or manufacture a permit in a non-eligible zone. The properties that work in this market are the ones bought in a zone where bachelorette and music-tourist traffic is not going anywhere, ideally with a transferable Type 2 permit.
The market-wide Nashville Airbnb occupancy rate of 54% is useful for one thing: understanding that Nashville clears the national average threshold on demand. Beyond that, it tells you nothing about your specific deal. The submarket spread runs from 27% in the bottom quartile to 85% at the top of Downtown and Gulch. Buying at the wrong point on that curve — and paying for the city's reputation rather than the neighborhood's actual performance — is the mistake we underwrite against before every offer. Our Nashville STR Underwriting Calculator exists specifically to avoid it.
That work is also why we were recognized by USA Today as Nashville's leading STR and investment advisor — because we tell clients the actual submarket numbers before the offer, not after.
Related reading
- Nashville STR Underwriting: The Occupancy Assumptions Smart Investors Use
- The Complete Nashville Short-Term Rental Investment Guide for 2026: Permits, Underwriting, Neighborhoods, and Exit
- Nashville STR Permit Guide: What Buyers Must Verify Before Going Under Contract
- Nashville STR Case Study: How We Use Verified DOM and Revenue Data to Prove a Premium
Frequently Asked Questions
What is the Nashville Airbnb occupancy rate right now?
Nashville's short-term rental market currently averages 54% occupancy across 13,898 active listings as of June 2026, at an average daily rate of $349, according to AirDNA. That figure is up 1.7% year-over-year on occupancy, though average daily rate and total revenue per listing are both down from the prior year. Submarket occupancy ranges from roughly 27% at the bottom quartile to 75–85% in Downtown, SoBro, and The Gulch.
Which Nashville neighborhood has the highest Airbnb occupancy rate?
Downtown Nashville and SoBro report the highest submarket occupancy figures, ranging from 75 to 85% according to BNBCalc submarket data. The Gulch follows closely at approximately 80%. These submarkets benefit from event-weekend group demand, walkability to Broadway, and corporate travel from nearby employers like Amazon, Oracle, and AllianceBernstein. East Nashville and Germantown run 72–75% with a different but durable guest profile.
Does Nashville STR occupancy hold up in January and February?
October is the strongest month for Nashville STR performance and January is the softest, so hosts should expect demand to move meaningfully throughout the year. However, Nashville never reaches a true off-season zero. There is no off-season in the strict sense — there are slower weeks, but the demand floor never drops to seasonal zero the way beach or ski markets do. Properties with strong reviews and dynamic pricing in core submmarkets still capture weekend bookings through the slower months. The lowest-performing weeks are typically the second and third weeks of January and February.
How much does bedroom count affect Nashville STR occupancy?
Strong four-bedroom homes near downtown gross $80,000 to $160,000-plus per year, while average listings earn near $40,000. The four-bedroom-with-rooftop-deck product dominates the group booking market that drives the highest occupancy in Downtown and The Gulch. Smaller units — studios and one-bedrooms — serve a corporate and solo traveler guest who books closer to the travel date and typically at lower ADR. Both can work, but bedroom count interacts directly with the dominant demand type in each submarket. Match product to submarket demand rather than buying what is available and hoping the calendar fills.
Do Nashville STR occupancy rates vary by event calendar?
Nashville's STR market is heavily event-driven, with peak demand running April through October, and June sees particularly high occupancy due to CMA Fest. In 2026, Alan Jackson's final concert at Nissan Stadium generated the second-highest room demand of any weekend to date in 2026, with 78,433 rooms sold and 92% occupancy county-wide and 98% downtown. For STR investors, this means event-adjacent properties can spike to two to three times their baseline rate on specific weekends — but underwriting on peak event revenue alone is how investors get burned. Model a realistic blended occupancy across all 52 weeks, not the top ten.
Can I get a NOOSTR permit in East Nashville or is it restricted?
Parts of East Nashville sit in or adjacent to eligible commercial and mixed-use zones, but much of the residential fabric does not qualify for new non-owner-occupied STR permits. New NOOSTR permits are only issued in commercial, mixed-use, office, and downtown zoning districts, which cluster within roughly three miles of Broadway. Buying an East Nashville property on the assumption it can be operated as a non-owner-occupied STR without confirming permit eligibility by parcel first is one of the most common and expensive mistakes we see. Always verify zoning at the property level, not the neighborhood level, before you are under contract. The Costigan Group verifies this as standard procedure for every STR client — more on our process is on our Nashville STR page.
How do I know if a Nashville STR deal is actually priced for its submarket occupancy?
Run RevPAR, not just occupancy. Take the submarket's realistic ADR — not the top performer's ADR — and multiply it by the submarket's actual occupancy rate, then back out 25 to 35 percent for operating costs. Underwriting with 25 to 35 percent operating costs and seasonal dips is the right model before trusting any revenue projection. If the resulting net income does not clear your debt service at current rates, the deal is not priced for what the submarket actually delivers. The 54% market average is not a safe assumption for most submarkets. Submarket-specific data is what the Costigan Group's Nashville STR Underwriting Calculator is built on. Learn more about how we advise investors at thecostigangroup.com.
About The Costigan Group
Jack Costigan is the founder of The Costigan Group at Compass in Nashville, where his team has closed more than $100 million in real estate across Greater Nashville and Middle Tennessee. Specializing in luxury advisory, investment, and short-term rental real estate, Jack is known for a data-driven approach that helps buyers, sellers, and investors understand the numbers, the neighborhood, and the long-term value before making a decision. Featured in Apple News as one of Nashville's most sought-after short-term rental advisors, Jack pairs deep local expertise with modern marketing and a strategy-first approach to real estate. Learn more at thecostigangroup.com.